

Spring 2027 Home Buying Season: Your Q4 2026 Action Plan for Tampa Bay First-Time Buyers
When does the spring home buying season start in Tampa Bay?
Tampa Bay's spring buying season typically kicks off in late February and peaks between March and May. Inventory rises as sellers list ahead of the school-year calendar, but buyer competition intensifies just as fast. First-time buyers who start their preparation in Q4 2026 — getting pre-approved, lining up down payment assistance, and building their team — put themselves ahead of the crowd that waits until January to begin.
Spring is the busiest, most competitive home buying season in Tampa Bay — and buyers who wait until March to start preparing almost always arrive late. Pre-approvals take time. Down payment assistance programs require lender enrollment. And the right agent, the right neighborhood research, and the right credit score don't happen overnight.
This is your Q4 2026 action plan: a step-by-step guide to everything Tampa Bay first-time buyers should do right now to be ready when spring 2027 inventory peaks.
Why Does Spring Make Home Buying Harder in Tampa Bay?
Every February, Tampa Bay listings jump as sellers time their sale to the school-year calendar. Families moving before August list in spring. Snowbirds returning north list in spring. New construction communities open new phases in spring.
More listings sound like a buyer's advantage — and they are, briefly. But buyer demand rises even faster. Multiple offers return. Homes in desirable neighborhoods go under contract within days, sometimes hours. Sellers in spring have more negotiating power than sellers in October or November.
Buyers who arrive in March already pre-approved, with a homebuyer education certificate in hand, with a lender enrolled in down payment assistance programs, and with a clear sense of which neighborhoods fit their budget — those buyers win. Buyers who arrive in March *just starting* their mortgage research routinely lose to buyers who are simply more prepared.
What Should You Do Right Now (October–December 2026)?
Step 1: Get Your Credit Report and Address Any Issues
Pull your free credit reports from all three bureaus at AnnualCreditReport.com. Look for errors, collection accounts, or high credit utilization dragging down your score. Most DPA programs require a minimum 640 credit score; conventional loans reward scores above 700 with meaningfully better rates.
If you find issues, you have roughly three to four months before spring shopping season begins — enough time to dispute errors, pay down revolving balances, or address collections with a pay-for-delete agreement. Three months of consistent on-time payments and lower utilization can move a score significantly.
Step 2: Estimate Your Budget and Down Payment Gap
Use your gross monthly income to estimate where you land on debt-to-income ratios. Most programs want your total housing payment (principal, interest, taxes, insurance, and HOA if applicable) at or below 45% of your gross monthly income. The 2026 FHA loan limit for Hillsborough County is $541,287 — helpful to know as a ceiling if you plan to use an FHA loan.
Once you have a rough purchase price range, calculate how much down payment you actually need. If your savings fall short, Q4 is the right time to explore:
- Florida Hometown Heroes — up to $35,000 for income-eligible buyers in qualifying professions
- County SHIP programs in Hillsborough, Pinellas, and Pasco — can add tens of thousands on top of state programs
- Florida Assist — up to $10,000 in deferred second mortgage assistance
Your lender can help you stack programs to cover the gap.
Step 3: Complete Your Homebuyer Education Certificate
Most Florida down payment assistance programs — including Hometown Heroes and HFA Plus — require a completed homebuyer education certificate from a HUD-approved provider. These courses cover budgeting, mortgage basics, and the closing process. They're typically available online and take four to eight hours to complete.
Getting this done now means you're not scrambling to finish a required course while you're also trying to schedule showings and make offers in March.
Step 4: Interview and Choose Your Lender
Not all lenders are enrolled in Florida Housing Finance Corporation programs. If you want access to Hometown Heroes, HFA Plus, Florida Assist, or county SHIP funds, you need a participating lender. Ask specifically:
- Are you a Florida Housing-approved lender?
- Can you originate Hometown Heroes loans?
- Have you closed loans using Hillsborough (or Pinellas, Pasco) SHIP funds?
Get a lender who says yes to all three before you get formally pre-approved in January or February. Q4 is also a good time to compare rates and lender fees — you're not on a deadline yet, so you can shop without pressure.
Step 5: Research Neighborhoods While Inventory Is Calm
Spring markets move too fast for leisurely neighborhood research. Use Q4 2026 — when homes sit longer and open houses are less crowded — to drive neighborhoods, attend open houses without pressure, and get a realistic sense of what your budget buys in different areas.
Compare commute times during rush hour, not on a Sunday afternoon. Check school ratings if that matters to you. Look at HOA fees and CDD fees in new construction communities. Walk or drive the neighborhood at different times of day.
Areas where Tampa Bay first-time buyers at various price points tend to find the best value include:
- Brandon and Riverview for single-family homes with access to I-75
- Wesley Chapel and Zephyrhills for new construction with builder incentives
- Plant City for USDA-eligible $0-down options in Hillsborough County
- Clearwater and Dunedin for Pinellas County buyers closer to the Gulf Coast
- New Port Richey and Hudson for the most affordable options in Pasco County
Step 6: Choose a Buyer's Agent Before the Rush
In spring, experienced buyer's agents in Tampa Bay are stretched thin showing homes to multiple clients. In Q4, you have time to interview two or three agents, review their recent buyer transaction history, and choose someone whose communication style and market knowledge match your needs.
Under Florida's current buyer agent agreement rules, you'll sign a representation agreement before touring homes. Do that in a calm, unhurried Q4 conversation — not standing in a driveway in March because a home just listed and you're trying to get in the same day.
Barrett Henry, REALTOR® with REMAX Collective, has helped Tampa Bay first-time buyers navigate the process with 23+ years of real estate experience. You can reach Barrett directly at (813) 733-7907.
Step 7: Build (or Protect) Your Down Payment Savings
The holiday season is notoriously bad for savings. Credit card spending in November and December can erode months of progress — and lenders will review your bank statements from the two to three months before closing. Unexplained large deposits or unusual spending patterns trigger questions during underwriting.
Set a holiday spending budget now. Park your down payment in a dedicated, separate savings account so it's clearly documented. If you're receiving a gift from family toward your down payment, connect your lender with the gift-giver in January so the gift letter and fund transfer are handled cleanly.
Is It Better to Buy Now or Wait for Spring?
Tampa Bay is currently a buyer's market — one of the more favorable environments for first-time buyers in recent years. Sellers are offering concessions, days on market are longer than in 2021–2023, and competition is manageable compared to what spring will bring.
If you're already pre-approved and find the right home in Q4 2026, there's a strong case to buy now rather than wait:
- Less competition from other buyers
- More negotiating power on price and seller concessions
- Homestead exemption starting January 1, 2027 (close before December 31)
- Seller motivation peaks in November–December for listings that haven't sold
If you're not yet pre-approved or haven't saved enough, use Q4 to prepare so you're ready to move quickly when the right spring listing hits.
Your Q4 2026 Checklist at a Glance
- [ ] Pull credit reports and address issues
- [ ] Calculate your purchase price range and down payment gap
- [ ] Research DPA programs you may qualify for
- [ ] Complete your homebuyer education certificate
- [ ] Interview Florida Housing-approved lenders
- [ ] Drive and research target neighborhoods
- [ ] Interview and choose a buyer's agent
- [ ] Set a holiday spending budget and protect your savings
Spring 2027 will be competitive. The buyers who win will be the ones who did this work now.
Ready to start your preparation? Barrett Henry, REALTOR® with REMAX Collective, has 23+ years of real estate experience helping Tampa Bay first-time buyers navigate programs, neighborhoods, and the full buying process. Call or text (813) 733-7907 to start the conversation today.
Want to see which programs you qualify for?
2-minute check, no credit pull, no commitment.
No credit pull · No obligation · Response within 2 hours · 23+ years experience
Frequently Asked Questions
When does the spring home buying season start in Tampa Bay?
Tampa Bay's spring buying season typically kicks off in late February and peaks between March and May. Inventory rises as sellers list ahead of the school-year calendar, but buyer competition intensifies just as fast. First-time buyers who start their preparation in Q4 2026 — getting pre-approved, lining up down payment assistance, and building their team — put themselves ahead of the crowd that waits until January to begin.
Should I wait until spring 2027 to start my home search in Tampa Bay?
Not if you want to be ready to make a competitive offer. Pre-approval takes time, down payment assistance programs require lender enrollment, and homebuyer education certificates (required for most DPA programs) take a weekend course to complete. Starting now means you'll be fully prepared when spring inventory peaks, rather than scrambling to catch up while the homes you want go under contract. If you find the right home in Q4 2026, Tampa Bay's buyer's market means you may get better terms now than you will competing in spring.
Do Florida down payment assistance programs reset or change at the start of the year?
Yes. Florida Housing Finance Corporation programs — including Florida Hometown Heroes, Florida Assist, and HFA Plus — receive funding allocations that can run out during high-demand periods and may be replenished or adjusted annually. Some lenders participating in these programs also have program-year enrollment windows. Starting your pre-approval process in Q4 2026 ensures your lender confirms current availability and locks in your eligibility before any potential funding changes at the start of 2027.
How does buying in Q4 2026 vs. spring 2027 affect my homestead exemption?
If you close and take possession of your Tampa Bay home before December 31, 2026, you qualify for the Florida homestead exemption for the 2027 tax year — provided you file Form DR-501 with your county property appraiser by March 1, 2027. Buyers who wait and close in spring 2027 miss that entire year of exemption savings, which typically reduce your taxable value by at least $50,000 and cap future tax increases under the Save Our Homes limitation. That's one year of property tax savings you can't recover.
How long does mortgage pre-approval last in Florida?
Most mortgage pre-approvals are valid for 90 to 120 days, and lenders require updated documents if your pre-approval expires before you close. For buyers aiming at spring 2027, the ideal window to get pre-approved is January through February 2027. However, starting conversations with a lender in Q4 2026 gives you time to address any credit or documentation issues before you formally apply, so your pre-approval comes back as strong as possible.
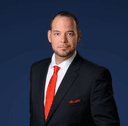
Barrett Henry, REALTOR®
Broker Associate with REMAX Collective. 23+ years of real estate experience. Helping Tampa Bay first-time buyers access down payment assistance programs most agents don't know exist.
(813) 733-7907Barrett Henry is a licensed real estate Broker Associate with REMAX Collective, not a mortgage lender. Program terms and funding are subject to change. Confirm current eligibility with a participating lender.
Free resources:
HUD Housing Counseling: 1-800-569-4287 · FHA Resource Center: 1-800-225-5342 · HOPE Hotline: 1-888-995-4673
Ready to take the next step?
Barrett matches first-time buyers with down payment programs at no cost. 23+ years of real estate experience.